Context
The Motability Scheme addresses the market failure in the provision of suitable transportation for disabled people, from limited access to cars to the cost of adapted vehicles and access to insurance.
There is a transport accessibility gap today. The difference between journeys undertaken by people with mobility difficulties and those without has been stuck at around 38% for a decade.
Public and commercial transport options for disabled people are still inadequate, reflected in the concentration of Motability customers in suburban or rural areas (81%).
VAT
UK VAT law (VAT Act 1994) includes provisions specifically designed to support disabled people through VAT relief on Motability Scheme leases and end-of-lease vehicle sales where they are linked to qualifying mobility benefits.
100% of the value of the VAT relief is passed through to disabled people who lease vehicles on the Scheme through lower lease prices. It is targeted support for disabled people that the Scheme administers on behalf of government. The Scheme is designed to operate with a small margin and any financial surpluses are reinvested into the Scheme or used to support disabled people’s mobility.
The Scheme’s structure is fully compliant with VAT law, with oversight from HMRC and DWP.
Recent changes to VAT and Insurance Premium Tax
The Government changed the tax treatment of the Motability Scheme in the 2025 Autumn Budget. From 1 July 2026, VAT at 20% applies to Advance Payments and certain other charges on new leases, while the Scheme’s exemption from Insurance Premium Tax (IPT) was also removed. Wheelchair Accessible Vehicles and certain heavily adapted vehicles continue to receive specific protections.
The core lease payment funded by a customer’s qualifying mobility allowance continues to receive VAT relief, as does the sale of vehicles at the end of their Scheme lease.
Without changes to the Scheme, the new taxes would have added around £300 million a year to its costs – equivalent to around £1,100 on an average lease. Motability Operations changed parts of the leasing package to offset around £700 of that cost, limiting the average additional cost to customers to around £400 over a three-year lease. Existing leases were not affected by the changes.
Removing the remaining VAT relief
Removing the remaining VAT relief would add significant costs to Scheme leases, potentially making affordable mobility inaccessible to thousands of disabled people.
New modelling illustrates the potential impact:
- Removing VAT relief on end-of-lease vehicle sales alone could increase upfront Advance Payments by around £3,320. This could reduce new applications to the Scheme by approximately 74%.
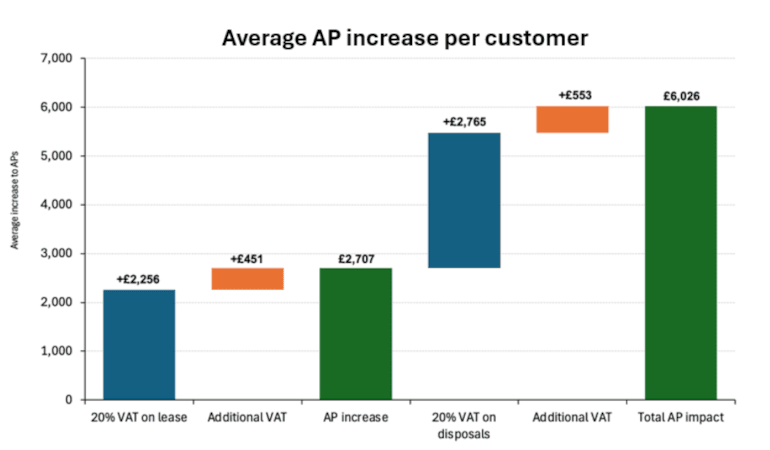
- Applying 20% VAT to both lease payments and end-of-lease vehicle sales could increase upfront Advance Payments by approximately £6,000. At this level, modelling suggests that almost all demand for the Scheme could disappear, leaving it accessible primarily to those able to afford the additional costs.
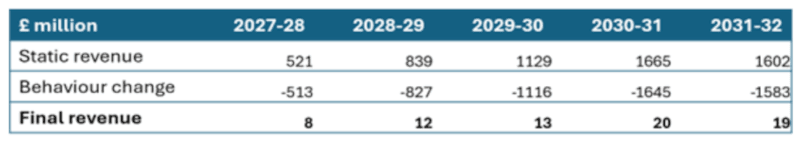
- The Treasury could raise substantially less revenue than anticipated. While the combined measures could theoretically generate around £1.7 billion a year if customer numbers remained unchanged, modelling suggests revenue could fall to around £20 million annually once reduced demand is taken into account.
These figures are illustrative estimates based on modelling undertaken before the July 2026 tax changes. Given the unprecedented price increases involved, the precise impact on customer demand is uncertain.


Note: These estimates are illustrative. While the precise figures are subject to uncertainty given the scale of the price increases, the modelling demonstrates the likely outcome: a substantial reduction in customers using the Scheme, significantly reducing the tax revenue the Government would collect.
A spokesperson for the Motability Scheme said:
"The Motability Scheme exists to enable freedom and independence for disabled people. The VAT relief that remains is passed directly to disabled customers through lower lease prices. Removing it would add thousands of pounds to the cost of mobility and risk making a car unaffordable for many disabled people, fundamentally undermining the purpose of the Scheme."
The median household income of a disabled person using the Scheme is around £18,500 – about half the UK average (£36,700). Significant increases in upfront costs would therefore be unaffordable for many customers.
Disabled people cannot simply turn to the private market. Research shows that around 60% of Scheme customers would struggle to access conventional credit, while around 30% would find it difficult to access insurance without the Scheme.
The Scheme operates at scale, allowing bulk purchasing and strong manufacturer discounts that help keep leases affordable. A significant reduction in participation would erode these efficiencies and threaten the specialist market for wheelchair accessible vehicles, which relies on the purchasing power of the wider Scheme. It would also have knock-on consequences for vehicle purchases, dealerships, manufacturers and jobs across the UK automotive sector.